October 16, 2026
Recommended
Event
Low-Income Countries and the IMF in a Changing World
HYBRID
October 14, 2026 4:30—5:45 PM +07 | 5:30—6:45 AM EDT |10:30—11:45 AM BST
Blog Post
From Debt to Growth
October 07, 2026
Topics
CITATION
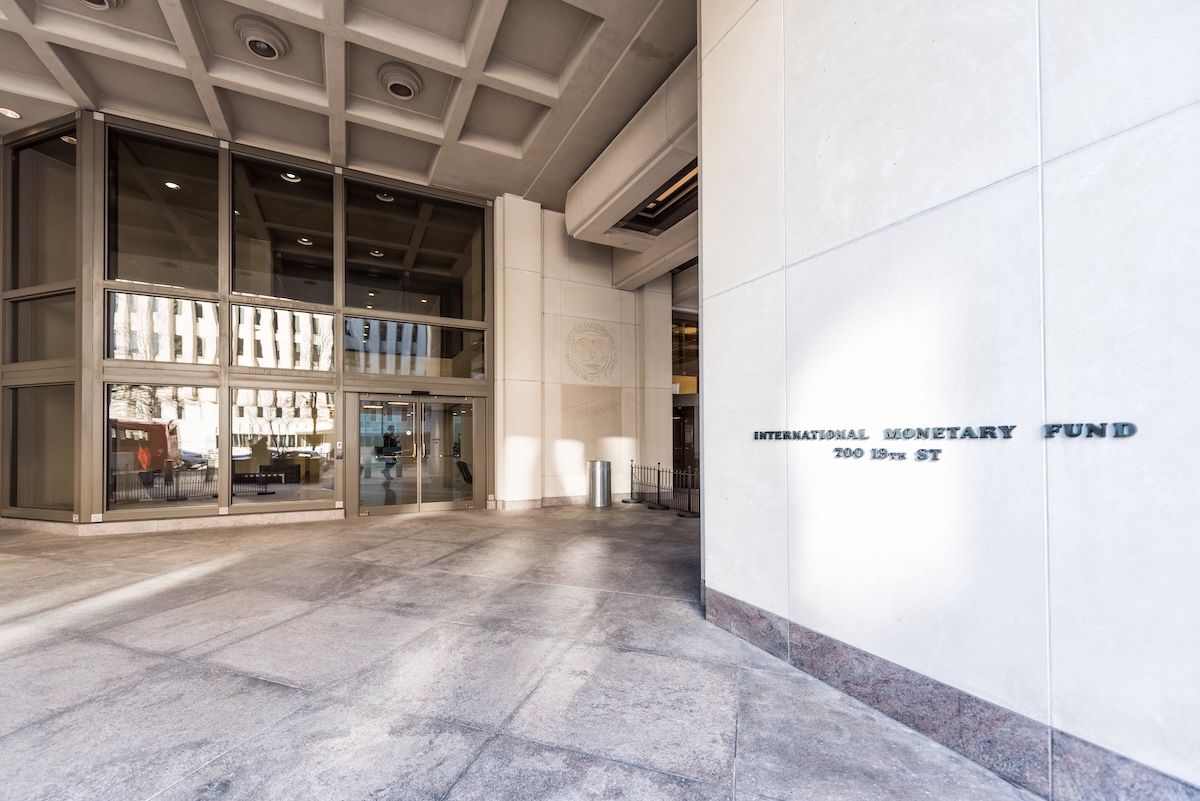
Pattillo, Catherine. 2026. A Shift Toward Net Repayment? Low-Income Countries’ Changing Net Financial Relationship with the IMF. Center for Global Development.DISCLAIMER & PERMISSIONS
CGD's publications reflect the views of the authors, drawing on prior research and experience in their areas of expertise. CGD is a nonpartisan, independent organization and does not take institutional positions. You may use and disseminate CGD's publications under these conditions.
Thumbnail image by: spiritofamerica/ Adobe Stock